Esta empresa não tem vagas ativas no momento
0 Avaliações
Avalie esta empresa ( No reviews yet )

Allbio
(0)Information Company
- Total Jobs 0 Vagas
- Full Address 455 Petunia Way
Detalhes da Empresa
Understanding Personal Loans For Poor Credit: A Comprehensive Case Study
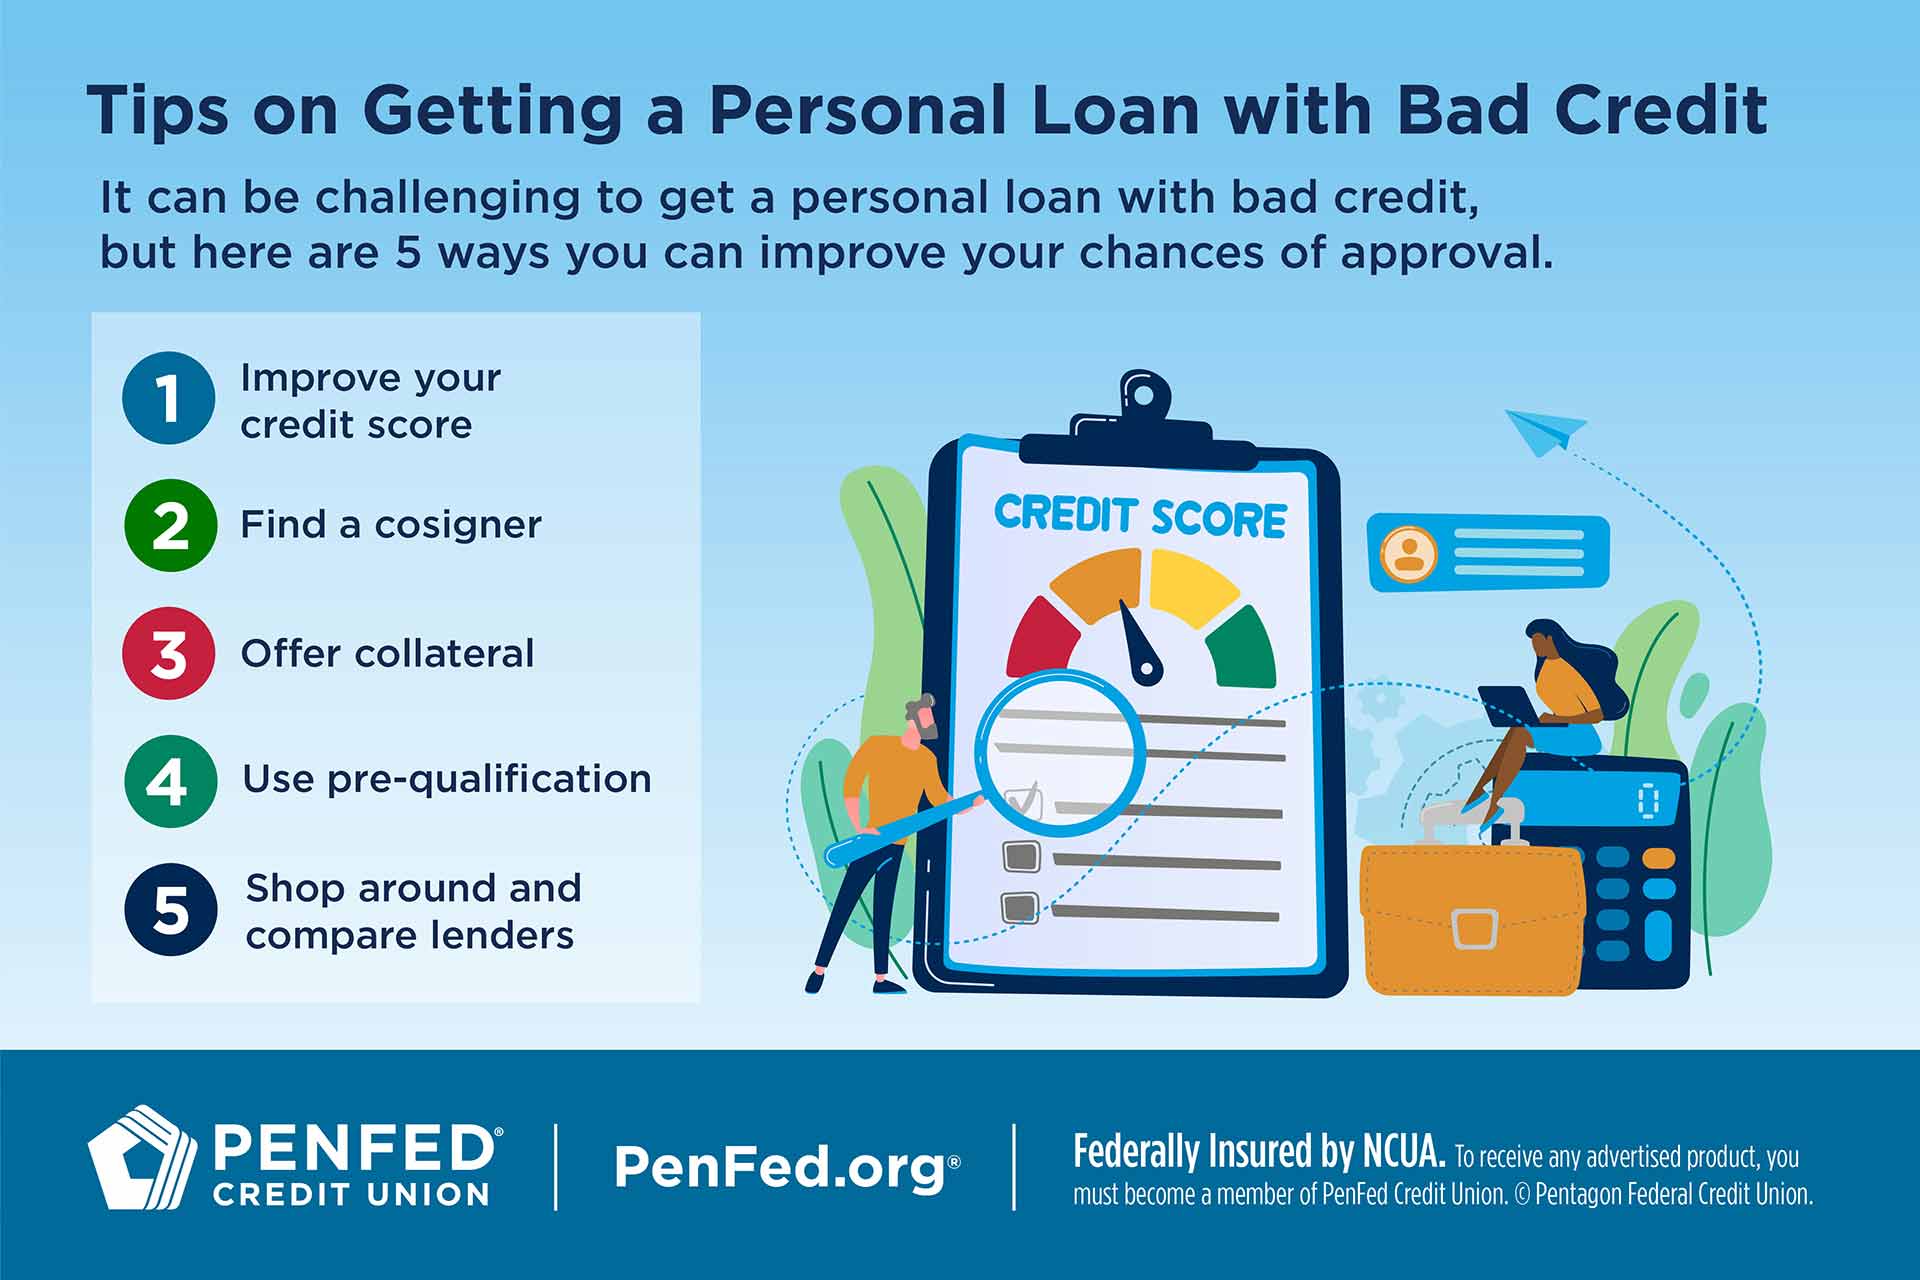
In right this moment’s monetary landscape, entry to credit score will be a big problem for people with poor credit scores. A poor credit score score—typically defined as a rating below 580 on the FICO scale—can be a considerable barrier, stopping many from acquiring personal loans. Nonetheless, understanding the choices accessible and the implications of taking on debt with poor credit score can assist people make knowledgeable monetary selections. This case examine delves into the realities of personal loans for poor credit by examining a hypothetical individual’s state of affairs, their choices, and the potential outcomes.
Background
For the aim of this case examine, we’ll refer to our hypothetical topic as Alex. Alex is a 30-year-outdated single parent who works full-time in retail. Over the previous few years, due to unexpected circumstances, including medical emergencies and job instability, Alex’s credit score has dropped to 550. With limited financial savings and an unexpected automobile breakdown, Alex found themselves needing a personal loan to cover restore prices and keep financially afloat.
The Challenge
Alex’s poor credit score rating posed a major barrier to accessing traditional banking services. Many lenders view low credit scores as an indicator of high danger, and as a result, they typically deny purposes or provide loans with exorbitant curiosity charges. Pissed off however determined, Alex started to explore choices available for personal loans despite the poor credit scenario.
Loan Choices Explored
- Secured Personal Loans:
Secured loans require collateral, which makes them less dangerous for lenders and infrequently leads to raised terms for borrowers. However, Alex had limited belongings to make use of as collateral, which made this feature less viable.
- Credit Unions:
Native credit unions usually provide extra enticing terms for individuals with poor credit score histories compared to traditional banks. After some analysis, Alex found a close by credit score union prepared to work with people with low credit scores. The loan was for $2,000 with a 12% curiosity charge, considerably lower than many various lenders. However, the loan required membership—a challenge for Alex who had restricted funds for initial fees.
- Online Lenders:
Online lending platforms cater to individuals with poor credit, claiming a streamlined process and quick approvals. Many supply loans without requiring a credit score verify. One such platform offered a $2,500 loan at an interest price of 24%. Whereas the approval process was simple, Alex anxious concerning the long-time period burden of the high interest.
- Payday Loans:
Unsurprisingly, payday loans emerged as an choice. Whereas they were easy to obtain, payday loans include exorbitantly excessive curiosity rates and are sometimes due within a brief repayment period (usually one payday cycle). Alex averted this route after studying in regards to the debt cycle that always ensues from failing to repay such loans.
Choice-Making Process
With a number of choices on the desk, Alex faced an important decision. Weighing the professionals and cons of each choice was necessary—especially contemplating lengthy-term repercussions on financial well being. Alex prioritized security and affordability moderately than speed, acknowledging that repaying a loan with high-curiosity rates might result in worsening financial stress.
Ultimately, Alex chose the option from the credit union. Whereas it required membership charges, the lower curiosity fee made it extra manageable in the long term. Alex calculated the monthly payment and determined it was doable inside their budget, given their present income and expenses.
Loan Affect and Administration
After securing the loan, Alex used the funds to restore the automotive, which enabled dependable transportation to work. Consequently, Alex began to handle funds more proactively. They established a month-to-month price range, making certain the loan funds were made on time to avoid late charges that might additional injury credit score.
Recognizing the importance of improving their credit rating for future alternatives, Alex dedicated to monetary literacy. They researched debt administration strategies, consulted monetary coaches, and began exploring ways to extend earnings, comparable to in search of half-time opportunities or gig work.
Long-term Outcomes
Over the ensuing months, Alex saved up with the personal loan funds persistently. Because of this, by the top of the loan term, Alex’s credit score started to indicate signs of restoration, climbing to 620. This enchancment opened doorways to higher borrowing choices ought to a necessity come up sooner or later.
Reflecting on their experience, Alex realized that whereas a personal loan for poor credit score got here with challenges, it was also a possibility for growth. The necessity for quick cash had led to higher monetary habits, extra disciplined budgeting, and a dedication to improving creditworthiness.
Conclusion
For people like Alex, personal loans can function a crucial financial software when managed correctly. The journey to acquiring a personal loan with poor credit might be fraught with challenges, but with the proper research and a commitment to accountable monetary behavior, it is feasible to navigate by way of efficiently.
The important thing takeaways from Alex’s expertise embody the importance of exploring numerous lending options, understanding the phrases of loans, and maintaining a finances to manage repayments effectively. Personal loans, whereas potentially dangerous, can facilitate instant needs and catalyze lengthy-term monetary improvement when approached with care and data.
In a broader context, this case underlines the significance of monetary education for people with poor credit score and advocates for higher lending practices that accommodate borrowers’ various circumstances. By doing so, society can foster financial inclusiveness and assist raise many out of monetary distress.
