Esta empresa não tem vagas ativas no momento
0 Avaliações
Avalie esta empresa ( No reviews yet )

Curry Pot
(0)Information Company
- Total Jobs 0 Vagas
- Full Address Gesausestrasse 65
Detalhes da Empresa
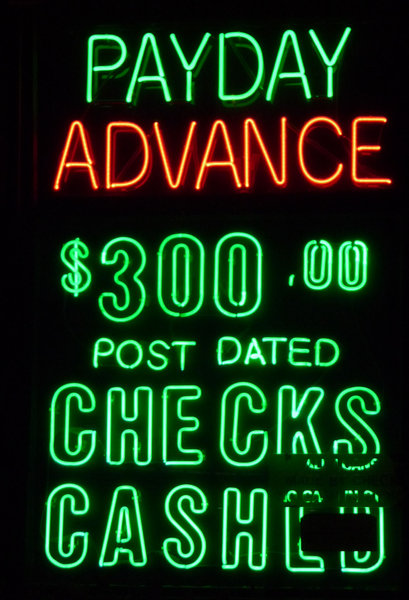
The Evolution of Payday Loans: From Predatory Practices to Responsible Lending Options
Payday loans have lengthy been related to high curiosity rates and exploitative lending practices. Historically, these quick-term, excessive-price loans were designed to offer fast cash to borrowers in need of speedy funds, usually resulting in a cycle of debt that trapped many individuals in monetary hardship. Nonetheless, a demonstrable advance within the payday lending sector has emerged, pushing the panorama in direction of extra responsible and sustainable lending practices. This evolution could be attributed to a mix of regulatory adjustments, technological innovation, and a rising give attention to shopper monetary wellness.
Historically, payday loans had been characterized by exorbitant interest rates, often exceeding 400% APR. This made it extremely difficult for borrowers to repay their loans on time, leading to a vicious cycle of re-borrowing and escalating debt. In response to widespread criticism and mounting evidence of predatory practices, lawmakers and regulators began to take motion. The introduction of stricter legal guidelines in varied states aimed to protect customers from these predatory practices, establishing limits on interest rates and fees, and mandating clearer disclosures about loan terms.
Moreover, a major advance has been the rise of accountable lending alternate options that cater to the identical demographic however prioritize borrower properly-being. A number of fintech companies and credit score unions have stepped into the fray, offering low-curiosity loans, installment plans, and revolutionary financial products that do not rely on predatory practices. These alternate options are significantly extra affordable, typically featuring APRs starting from 6% to 36%, allowing borrowers to repay their loans extra manageably and without the risk of falling right into a debt lure.
For example, companies like Earnin and Dave have utilized technology to create apps that enable customers to access earned wages forward of payday with out incurring hefty fees. Customers can get advances in opposition to their hourly wages, which they repay out of their subsequent paycheck, considerably reducing the monetary strain. This mannequin addresses the core financial want of immediate cash move whereas promoting responsible habits by permitting individuals to keep away from conventional payday loans altogether.
Moreover, the proliferation of peer-to-peer lending platforms has also contributed to this shift. These platforms join borrowers straight with individual lenders, usually at lower charges than traditional payday lenders. Know-how facilitates a direct lending market that’s extra clear and competitive. The use of knowledge analytics and machine studying to evaluate creditworthiness also signifies that these platforms can provide extra personalized lending choices based mostly on individual monetary profiles, making it simpler for borrowers to entry funds without falling into debt.
A notable instance of this innovation is the emergence of “salary-linked” loans. This concept allows borrowers to obtain loans which might be directly linked to their wage cycles, minimizing the chance of overloading borrowers with obligations they can’t meet. As modern cost buildings, these loans may be extremely beneficial for those going through unexpected bills while ensuring that the repayment aligns with their revenue timing.
Moreover, financial training has become a crucial a part of the conversation surrounding payday loans. With a significant portion of payday borrowers possessing restricted monetary literacy, many of the newer corporations now incorporate financial education into their service choices. This will include budgeting instruments, financial savings recommendation, and pre-loan counseling. If you have any inquiries about where and how to use Curry Pot, you can speak to us at our own web site. By equipping borrowers with information, these companies goal to empower people to make knowledgeable monetary selections, cultivating lengthy-time period monetary stability.
A serious hurdle that the payday lending industry continues to face, nevertheless, is the stigma related to borrowing. Many individuals still understand payday loans as a final resort, no matter their circumstances. Financial education initiatives additionally play a necessary role in dismantling this stigma. When borrowers perceive the wide selection of financial merchandise accessible to them, they are more likely to hunt down options that aren’t predatory—enabling them to regain management over their finances.
Moreover, the regulatory environment continues to evolve, with ongoing discussions about higher protecting consumers from payday lending abuses. While some states have enacted complete reforms, others still enable high-interest loans to operate freely. Advocacy groups proceed to push for nationwide standards that might prohibit predatory lending practices and require lenders to interact in responsible lending. This could embrace capping interest rates, mandating suitability assessments to make sure borrowers can afford to repay their loans, and implementing clear loan disclosures.
On the research entrance, varied studies and reports have begun to doc the constructive outcomes related to responsible lending alternatives in comparison with traditional payday loans. Analysis findings point out that borrowers who utilize low-cost, installment loans as a substitute of payday loans are much much less more likely to fall into further monetary distress. This reinforces the concept accessible, responsibly structured loans can indeed provide a lifeline in times of financial distress without leading to an unsustainable debt cycle.
In conclusion, the payday loan business is witnessing a pivotal shift in direction of more accountable lending, evidenced by both regulatory reforms and the rise of different merchandise. The introduction of fair lending practices, coupled with a heightened give attention to consumer schooling and technology, is step by step transforming the sector from its previously predatory roots to a more sustainable mannequin. Because the dialog surrounding financial wellness continues to evolve, it’s paramount for stakeholders—borrowers, lenders, and regulators alike—to stay vigilant in selling moral practices that prioritize the long-time period financial well being of individuals. In doing so, they might help reshape the narrative around payday loans, in the end facilitating a extra equitable finance ecosystem and empowering customers to make knowledgeable monetary decisions that foster stability and development.